About MetRisk Services
A fee-only advisory built on 25 years inside commercial insurance.
Insurance is bought on trust. We exist so it can be bought on evidence.
Most clients we work with had a broker they liked. That was never the question. The question was whether anyone had ever checked the program against the risk.
Where this came from
We didn't leave the industry. We built the part of it that is paid only by the buyer.
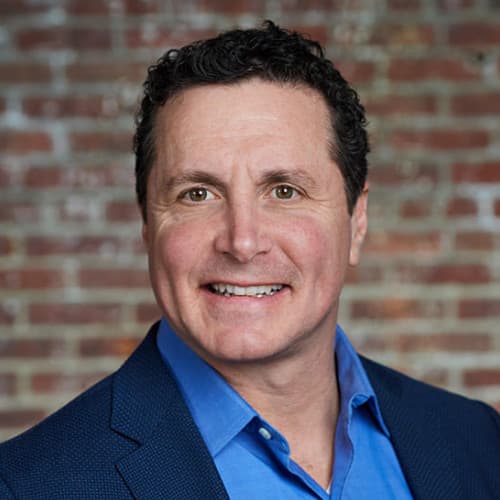
Michael Stoop
Founder, MetRisk Services
- 25 years as a commercial insurance broker
- Risk management and commercial insurance consulting
Twenty-five years as commercial brokers, placing coverage for mid-market construction and real estate companies, showed us what the buyer never gets to see. Commission carries a conflict that is structural, not personal: when your premium goes up, broker revenue follows.
The conflict is structural, not personal. When compensation scales with premium, the easy placement and the profitable one are the same placement, and nothing in the standard relationship makes anyone check. MetRisk Services is our answer to that: a separate firm where commission is out of the advice altogether, and where every broker's commission in your market process is shown to you in writing.
MetRisk Services is the advisor we would have wanted as buyers: paid only by you, no financial stake in which carrier wins, and the bias-removal logic in writing — not just claimed in a pitch deck. Risk Rocket 365, our renewal method, is that conviction applied to a single renewal, start to finish.
Michael also owns Metropolitan Risk Advisory, a licensed commercial insurance brokerage in New York and New Jersey, founded in 2010. That is where the 25 years come from, and it is why this firm exists as a separate company. MetRisk Services never places insurance and is paid only by its clients. Metropolitan Risk Advisory is a licensed broker, paid by carriers or by fee, and it is not on a MetRisk market list unless you put it there. If you do, it competes on identical terms, every quote is scored against your Blueprint in front of you, and what it would earn is disclosed to you in dollars before you decide. Our fee is the same whoever wins.
We've taken control away from the industry and put it back where it belongs — with you. Fee-only is not a marketing angle; it is a disclosed operating policy. See below.
Disclosed policy
Fee-only, disclosed as policy — not as a slogan.
Fee-only is the product, not a feature: commission-based advisors cannot replicate it without restructuring their revenue model. Their earnings scale with your premium; ours don't. That's structure, not positioning.
The policy
- Flat annual fee — never a percentage of your premium
- Broker commission disclosed on every quote, in writing
- No contingency payments, overrides, or profit-sharing
The placing broker earns a standard commission
Our fee does not change based on which quote you accept
We take nothing from the carrier side
You can ask to see this in writing
Wondering what it costs? A fixed fee based on the complexity of your program. We quote it plainly in the first conversation, which costs you nothing.
Start the free program analysisDue diligence
Ask any advisor — including us — these five questions.
Before you hire anyone to advise on your insurance program.
- 01Who pays you, and does it change based on what I buy?
- 02Will you disclose the broker's commission on every quote, in writing?
- 03Do you accept contingency payments, overrides, or profit-sharing from any carrier?
- 04Is your fee identical no matter which option I choose?
- 05Will you put all of this in writing before I sign?
Our answers are on this page. If another advisor can't answer all five in writing, you've learned what you needed to know.
The comparison
Why this is different.
Ten questions. Five kinds of advisor. One clear answer.
| Traditional broker | National broker with in-house risk team | AI-powered brokerage | In-house risk manager | MetRisk | |
|---|---|---|---|---|---|
| Who verifies your current broker's diligence | No one — you take it on trust | No one — their risk team works inside the same firm | No one — they're built to replace your broker, not audit them | No one — the risk manager is typically the broker relationship, not an auditor of it | We do, explicitly, before anything else happens. |
| Who pays us | Carrier commission | Carrier commission, with the risk services bundled in | Carrier commission or platform fee | Your company (salary + benefits) | You, flat fee only |
| What happens if your premium goes up | They earn more | They earn more, including the team that services your account | Usually still tied to premium | No direct incentive either way — but limited sight lines into the competitive market | We earn the same |
| What you're compared against | Just the quotes that come in | Just the quotes that come in | Just the quotes that come in | Their knowledge and relationships — hard to audit independently | Your current program + your own Blueprint spec, defined before any quote exists |
| How markets are allocated | Broker submits to their preferred markets — no coordination | Their own carrier relationships | Algorithm selects participating carriers | Depends on their broker relationships — no external coordination layer | We assign carriers to brokers before any contact — each carrier approached once, by the relationship best positioned to reach it. No duplicate submissions. |
| Who decides which carrier relationship to use | They do, from their own relationships | They do, from one firm's relationships | The platform's own carrier relationships | Their preferred broker's relationships — one step removed but still a single point of discretion | No single relationship decides — every broker on the panel is blind to the others. |
| After you bind coverage | Nothing until next renewal | Often claims advocacy and loss control, run by the firm that earns on your premium | Nothing until next renewal | Often yes — but typically focused on internal risk management, not carrier advocacy | Active claims compression working to improve your position for next time |
| Who's accountable | A commissioned salesperson | A service team inside the brokerage | An algorithm or call center | An employee — with limited specialization in competitive market dynamics | A named advisor, disclosed relationship on every quote |
| Program visibility (Total Cost of Risk) | Whatever your broker reports — usually just premium | Their reporting, on their platform | Platform dashboard, limited to their data | Often comprehensive — but internal, hard to audit externally | Full view: premiums, open reserves, loss ratio trend, experience mod trajectory, and cost-per-outcome — updated throughout the program. |
| What you have to give up to use us | N/A — already your broker | Nothing if they're already yours; otherwise, your current broker | Your existing broker relationship — they become your broker of record | N/A — separate function | Nothing — we work alongside whoever you already have. |
Who verifies your current broker's diligence
MetRisk
We do, explicitly, before anything else happens.
- Traditional broker
- No one — you take it on trust
- National broker with in-house risk team
- No one — their risk team works inside the same firm
- AI-powered brokerage
- No one — they're built to replace your broker, not audit them
- In-house risk manager
- No one — the risk manager is typically the broker relationship, not an auditor of it
Who pays us
MetRisk
You, flat fee only
- Traditional broker
- Carrier commission
- National broker with in-house risk team
- Carrier commission, with the risk services bundled in
- AI-powered brokerage
- Carrier commission or platform fee
- In-house risk manager
- Your company (salary + benefits)
What happens if your premium goes up
MetRisk
We earn the same
- Traditional broker
- They earn more
- National broker with in-house risk team
- They earn more, including the team that services your account
- AI-powered brokerage
- Usually still tied to premium
- In-house risk manager
- No direct incentive either way — but limited sight lines into the competitive market
What you're compared against
MetRisk
Your current program + your own Blueprint spec, defined before any quote exists
- Traditional broker
- Just the quotes that come in
- National broker with in-house risk team
- Just the quotes that come in
- AI-powered brokerage
- Just the quotes that come in
- In-house risk manager
- Their knowledge and relationships — hard to audit independently
How markets are allocated
MetRisk
We assign carriers to brokers before any contact — each carrier approached once, by the relationship best positioned to reach it. No duplicate submissions.
- Traditional broker
- Broker submits to their preferred markets — no coordination
- National broker with in-house risk team
- Their own carrier relationships
- AI-powered brokerage
- Algorithm selects participating carriers
- In-house risk manager
- Depends on their broker relationships — no external coordination layer
Who decides which carrier relationship to use
MetRisk
No single relationship decides — every broker on the panel is blind to the others.
- Traditional broker
- They do, from their own relationships
- National broker with in-house risk team
- They do, from one firm's relationships
- AI-powered brokerage
- The platform's own carrier relationships
- In-house risk manager
- Their preferred broker's relationships — one step removed but still a single point of discretion
After you bind coverage
MetRisk
Active claims compression working to improve your position for next time
- Traditional broker
- Nothing until next renewal
- National broker with in-house risk team
- Often claims advocacy and loss control, run by the firm that earns on your premium
- AI-powered brokerage
- Nothing until next renewal
- In-house risk manager
- Often yes — but typically focused on internal risk management, not carrier advocacy
Who's accountable
MetRisk
A named advisor, disclosed relationship on every quote
- Traditional broker
- A commissioned salesperson
- National broker with in-house risk team
- A service team inside the brokerage
- AI-powered brokerage
- An algorithm or call center
- In-house risk manager
- An employee — with limited specialization in competitive market dynamics
Program visibility (Total Cost of Risk)
MetRisk
Full view: premiums, open reserves, loss ratio trend, experience mod trajectory, and cost-per-outcome — updated throughout the program.
- Traditional broker
- Whatever your broker reports — usually just premium
- National broker with in-house risk team
- Their reporting, on their platform
- AI-powered brokerage
- Platform dashboard, limited to their data
- In-house risk manager
- Often comprehensive — but internal, hard to audit externally
What you have to give up to use us
MetRisk
Nothing — we work alongside whoever you already have.
- Traditional broker
- N/A — already your broker
- National broker with in-house risk team
- Nothing if they're already yours; otherwise, your current broker
- AI-powered brokerage
- Your existing broker relationship — they become your broker of record
- In-house risk manager
- N/A — separate function
The objection
You don't have to fire anyone.
Some modern risk management platforms ask you to hand your whole insurance relationship to a new, unfamiliar company. We're advisory, not a brokerage: keep the broker you trust, and we add an independent check on top — if they're genuinely doing a great job, they can compete in your market process. Nobody has to be replaced for this to work.
In their words
What clients say about working with us.
The renewal method grew out of our claims advocacy and risk management practice — same team, same standard, between renewals as well as at them.
5 client stories · swipe →1–1 of 5 client stories
“When our Workers' Comp Experience Modification Rate (EMR) climbed above 2.0, we were facing a 50% premium increase that pushed our annual expenditure well into the seven-figure range. While other consultants and brokers simply threw up their hands—claiming our 'challenged' workforce made claim prevention impossible—MetRisk stepped in with their specialized 'Comp Care System.' In 18 months, they cut our EMR in half through aggressive claims management and staff training. Beyond the immediate savings, they transitioned us to a reward-based program that has returned over $1.3 million in dividends to our bottom line. MetRisk's unique combination of high-level systems and expert personnel delivered results that we simply could not have achieved on our own.”
“Before partnering with MetRisk, we relied on a consultant and a large, publicly traded broker who focused solely on shopping our account for better rates. When claims frequency began to climb, both parties essentially gave up, blaming the 'hard market' for our rising costs. We were being drained by nuisance and fraudulent claims that decimated our profitability. The MetRisk team stepped in with a radically different, aggressive strategy. By implementing their '48 Protocol' and taking direct control of the claims process, they reduced our incurred losses by a staggering 73%. This aggressive strategy allowed us to restructure our program and achieve a 40% premium reduction—even as our NYC multi-family real estate peers saw 15% increases. MetRisk is the strategic partner you need to turn claims into a competitive advantage.”
“We were facing a catastrophic claim after torrential rain flooded the entire 14-story 'A-line' of a building where we were repairing the parapet. Despite the extreme weather, management held us responsible because we were active on the roof. We immediately called MetRisk, and they activated their '911 Claim Protocol.' Within hours, they had an independent engineer on-site performing a forensic diagnostic. Their investigation proved that the building's infrastructure was at fault, completely exonerating our team. MetRisk is the partner you want in your corner when the stakes are highest.”
“During a major construction project for Nordstrom's, a contractor left a significant opening in the building's envelope secured only by plywood. Our pipes froze, flooding the building and causing extensive damage to our mechanical systems and tenant spaces. MetRisk mobilized an attorney and engineer over the weekend to investigate. Thanks to their expert intervention, we successfully transferred the entire liability back to the negligent contractor. MetRisk's rapid response didn't just mitigate damage; it protected our loss history and shifted a massive financial burden away from our company.”
“We're heavily involved in WRAP and CCIP programs, so maintaining a clean Experience Modification Rate (EMR) is critical to our bidding capacity. When our EMR unexpectedly spiked despite a clean claims history, MetRisk identified the anomaly immediately through their proactive weekly monitoring. They discovered that a WRAP Administrator on a specific CCIP project had incorrectly reported a significant claim against our ID number, coordinated the correction, and restored our rating before it impacted our business. Their expertise in year-round risk management is a game-changer.”
Where we go deep
One vertical at a time, deeply.
We work nationwide, and deep rather than wide — industries where the risk is complex enough that the difference between checked and unchecked shows up on the balance sheet.
The differentiation, in practice.
The six-stage renewal method, or how ongoing claims compression works.
Ready for an advisor with nothing to hide?
Fifteen minutes on your program, your loss record, and where the money is. You keep the findings either way, and nothing about your current arrangement changes because you looked.
Fifteen minutes with Michael Stoop, our founder. Nothing to prepare — bring the question you can't get a straight answer to.
Or call us now — 347.252.6150
Not ready for a conversation?
Take the blind-spot check
Ten questions about your own program, answered from memory in ninety seconds. Nothing uploads.
Get one policy reviewed, free
Send the policy you are least sure about. We read it against how you operate and send back the three findings with the most at stake, each tied to its page.
Run your own loss pick
Premium and losses in, your ratio against the 50% line out — one year is enough. Nothing is submitted to anyone.
Walk a full engagement
A sample account, start to finish — the blueprint, the gaps, the scored quotes, the decision. Judge the work before the pitch.
- Flat annual fee — never a percentage of your premium
- Broker commission disclosed on every quote, in writing
- No contingency payments, overrides, or profit-sharing